

[ad_1]
The insurance coverage business boasts a storied historical past courting again to the Code of Hammurabi (round 1750 BC), Roman maritime legislation and Lloyd’s coffeehouse on the River Thames (1688).
Notably, the longest-tenured property insurance coverage firm within the US (The Philadelphia Contributionship, 1752) was organized by Benjamin Franklin. From this founding father, we credit score the expression:
“An oz. of prevention is value a pound of treatment.”
The restrictions of indemnification
Today, digital applied sciences allow insurers to create sensible customer-centric working fashions, the likes of which Ben Franklin might solely dream of. However the business’s worth proposition – constructed on the precept of indemnification – now threatens long-term progress alternatives because the short-term price of doing enterprise skyrockets.
Any insurance coverage firm on the planet faces bleak realities. Think about the inflationary pressures working towards efforts to cut back prices. Buyer expectations for real-time capabilities. And modern product designs throughout all enterprise strains designed to ship a customized, mind-blowing buyer expertise at a aggressive worth.
Insurers should proceed to evolve their enterprise fashions merely to outlive. Applied sciences like synthetic intelligence (AI) and generative AI (GenAI) can supercharge this evolution, however the limitations of indemnification will proceed to sluggish momentum.
To hurry evolution, insurers must shift to a brand new worth proposition – predict and stop.
It’s time for insurance coverage to alter
Think about insurance coverage options for property & casualty or life insurance coverage that actively establish dangers an individual or enterprise can deal with to forestall a loss from occurring. Even 5 years in the past, such concepts appeared like science fiction. However now, fiction has change into actuality. For instance:
One thing has to alter.
Problem the established order
As we’ve seen with different technological breakthroughs, success comes from boldly difficult the established order.
Think about {that a} human would want to carry out one sum per second for 31.7 billion years to carry out the equal one-second calculations (teraFLOPs) of the world’s strongest “exascale” computer systems.
Retaining in thoughts these profound implications, it appears mindless to not make the most of this know-how. That’s particularly the case once we know indicators from smartphones and IoT gadgets might be harnessed to proactively establish conditions that trigger or worsen loss.
Now’s the time to problem the established order of indemnification. Rethink the concept that a loss ought to occur first earlier than a coverage of insurance coverage can reply.
Losses from pure disasters 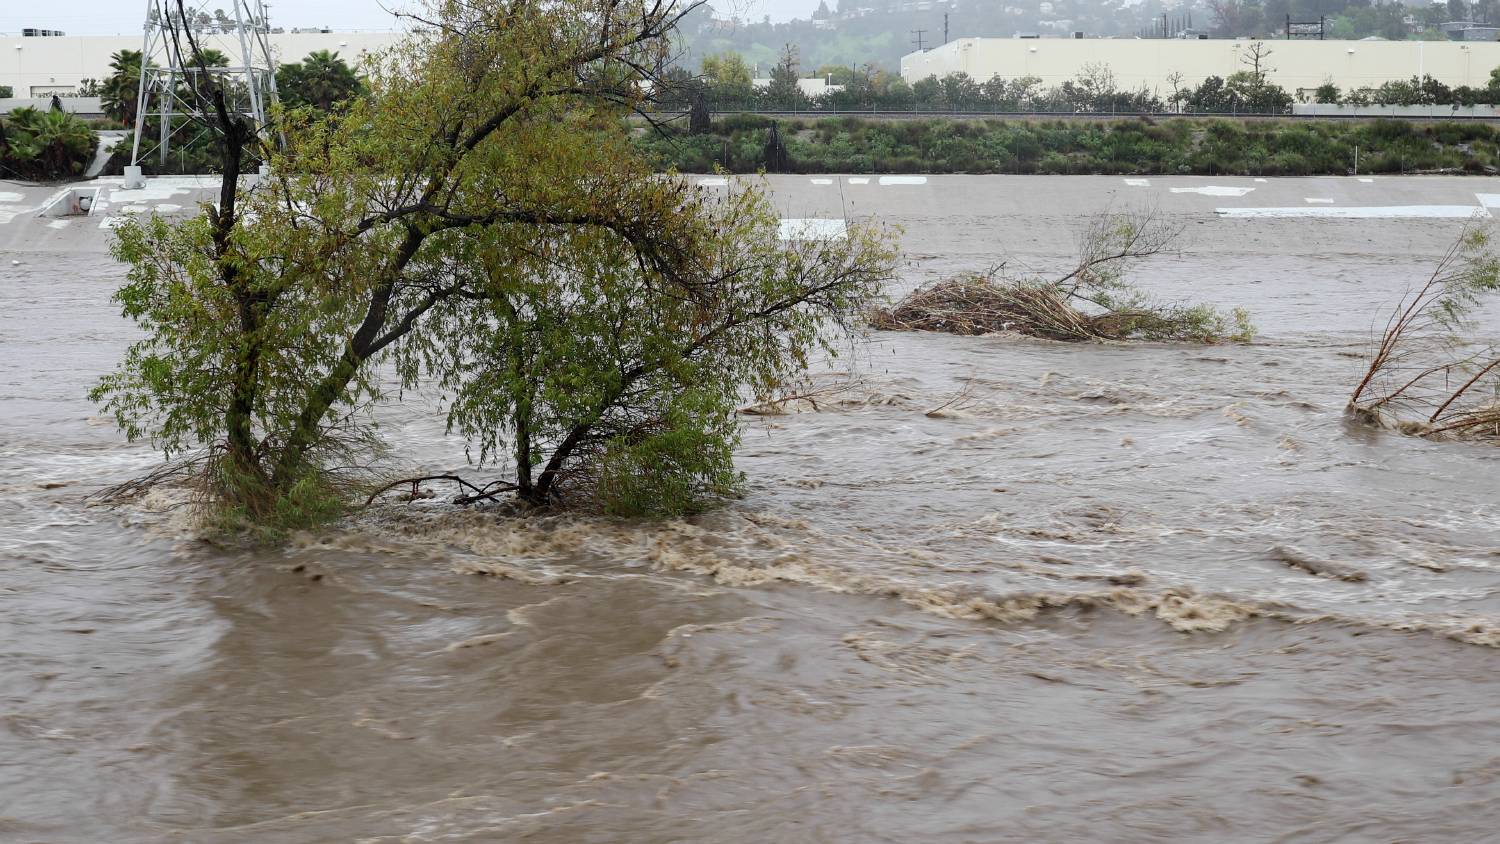
In its 2024 Local weather and Disaster Perception Report, Aon reported that international pure disasters in 2023 resulted in above-average financial losses totaling $380 billion. All over the world, insurers lined $118 billion and set a file variety of billion-dollar insured disasters. That 12 months was additionally the deadliest since 2010 (with 95,000 fatalities) and the most popular 12 months on file.
AI isn’t excellent – which shouldn’t hold us from utilizing it
Think about the insurance coverage business’s early response to “the web.” Way back, many insurers banned its use. However at this time, it’s widespread for insurers to look on-line for details about dangers in underwriting and claims processes.
We all know that not every thing on the web is true. Nevertheless it’s nonetheless helpful in gathering data. The trick is figuring out what’s dependable.
I had a front-row seat to a business underwriting audit wherein on-line misinformation put my group in jeopardy of a crit. Based mostly on a web-based picture, a strip mall we had insured appeared to have a tattoo parlor (a forbidden danger for our urge for food). Solely after I referred to as the enterprise did I be taught that the parlor had truly moved earlier than we insured the situation – so, there was no lack of disclosure.
AI is constructed by folks, and it’ll inherit our flaws. However just like what occurred with on-line searches, AI will permeate insurance coverage processes over time.
The important thing to fixing points with misinformation? It’s all concerning the information.
Keep in mind: The satan’s within the information
Insurers accumulate and retailer a veritable cornucopia of information. A person coverage might be rated on a whole lot, if not 1000’s, of variables – particulars concerning the named insured or enterprise proprietor, insured location, loss historical past, and so on.
Small inaccuracies can (and do lead) to main premium variations and a few dangers being accepted that by no means needs to be written. Some are outright declined.
This actuality exists as a result of the info is collected by coverage functions dealt with via conversations, typically on-line, typically through paper and (sure, nonetheless) typically even fax. Typically, the inaccuracies solely floor after a loss and after conducting a extra thorough investigation of the danger. If the data was initially collected by an agent, it might set off errors and omissions protection.
Sure, handbook assessment can discover 95% of errors, however doing so wastes folks’s time. So – typically the data used to write down a coverage isn’t validated.
More and more, third events – bureaus like Dun and Bradstreet – supply information and even information merchandise. Public data that’s accessible on-line can present deeper insights into particular person dangers.
The advantages? In line with McKinsey, carriers can obtain double-digit will increase in premiums and profitability by adopting “digitized underwriting.”
In these examples, by the use of an agent, or third celebration, the identical impediment stays – the data was collected by an middleman, fairly than immediately from the supply (the shopper). And since most information factors are proxies for danger, at finest, insurers are locked in a recreation of horseshoes and hand grenades: “Shut sufficient is sweet sufficient to win.”
Overcome chaos and make the most of new information
So how can we evolve to supply extra correct pricing fashions, underwriting choices, and claims experiences for folks and companies?
We have to look to new types of information (typically referred to as different information) to develop a greater understanding of dangers. In doing so, we are able to start stopping loss.
 Producing extra correct AI fashions
Researchers have demonstrated that AI can be utilized to generate extra correct fashions and an annual financial good thing about $162 billion. Such capabilities have been past us even only a few years in the past.
Due to the fast charge at which computing energy will increase – together with the widespread adoption of cloud computing – insurers can now receive large portions of information from new sources (like aerial imagery, IoT, public data and extra) to research through parallel processing, quicker than ever earlier than.
Knowledge about precise habits is superior to proxy information. Not too long ago, some automakers got here below scrutiny for permitting information to be shared with insurers. It’s no secret that at this time’s related automobiles retailer information about your driving. That information – harsh braking and acceleration, nighttime driving, dashing, and so on. – might be (and is) used to develop charges.
Knowledge can be used to step into the realm of accident and loss prevention. The scrutiny may be value it. Think about that:
The rise of UBI
Carriers have seen elevated participation in usage-based insurance coverage (UBI) applications (doubled from 2016 to 2023), and a 26% participation for brand new clients with a 59-point increased premium (worth) satisfaction in keeping with J.D. Energy.
Earlier this 12 months I participated in a program targeted on decreasing distracted driving via Cambridge Cellular Telematics (CMT). I bought to see firsthand how notifications diminished distracted driving – a notion I confirmed with the pinnacle of telematics at one US insurer operating an analogous program.
In CMT’s State of US Street Threat in 2024, information confirmed that the 4.5% lower in distracted driving in 2023 prevented greater than:
55,000 crashes.
31,000 accidents.
250 fatalities.
$2.2 billion in financial damages.
Refine and use your untapped information – and encourage change
Keep in mind the previous saying: “Knowledge is the brand new oil”? It’s a crude analogy (see what I did there), however nonetheless correct – since you’ve bought to extract oil out of the bottom, refine it, and finally distribute it for consumption and use.
Knowledge isn’t any completely different. Telematics or UBI information offers an untapped supply that insurers can (and will) use to evolve the business’s worth proposition.
State Farm has expanded its fireplace security program for 2 million households via Ting and Whisker Labs. State and native governments are enabling sensible cities applied sciences to ease visitors congestion and fight flood danger. And the Apple Watch has been credited with saving lives via the center charge app.
These tales encourage change within the business. All losses is not going to be prevented, however with the facility of AI, we are able to forestall some losses. The downstream impacts of assuaging loss pressures, saving lives and bettering financial worth will lead the business into a brand new period.
Learn concerning the high 5 insurance coverage issues – and why AI isn’t certainly one of them
SUBSCRIBE TO THE SAS INSIGHTS NEWSLETTER
[ad_2]
Source link


