

[ad_1]
I’ve been investing for a big a part of my life, and I’ve by no means seen detrimental sentiment like this earlier than. Not even throughout the latest two bear markets. First for the Covid-19 crash and later when the Fed went by a nasty rate of interest mountain climbing cycle to cope with inflation, which was for my part, self-inflicted. It must be famous that ”formally” each crashes didn’t include a recession, nevertheless, we do know that submit Covid the financial system shrank for the required two consecutive quarters, however there was debate over its classification as the roles market was sturdy. It is a little gray although, since this was authorities backed, identical to actual private disposable revenue that declined in 2022 and was offset by stimulus. So, in my thoughts, the federal government shot itself within the foot to keep away from a technical recession, which created a much bigger downside later down the road that we’re nonetheless coping with at present. Has a gentle touchdown been achieved? Or are we coming in sizzling?
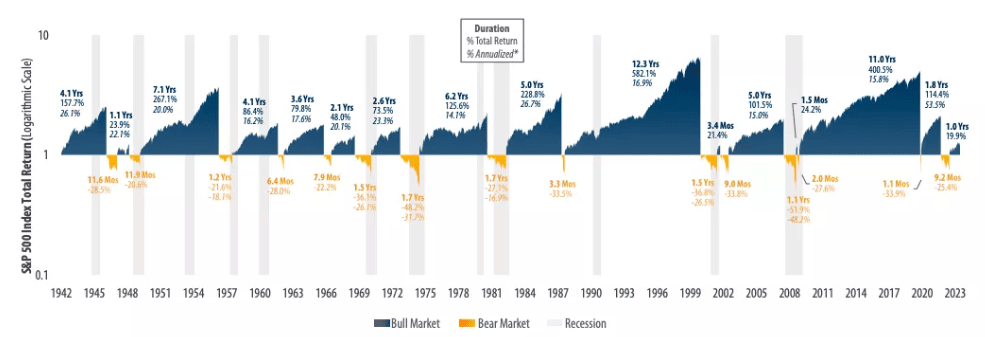
Bear markets by historical past – 56% coincided with recessionSource: Investopedia
this current correction, the S&P 500 dropped simply over 10% in 16 buying and selling days. On common, corrections of this dimension since 1950 have taken roughly 39 days. I believe the velocity of this drop is probably going what’s inflicting extra panic to construct. Different crashes that occurred at this velocity post-2000 embrace the 2008 monetary disaster, debt ceiling disaster, Fed hike cycle, and COVID-19 crash. All these occasions have been a powerful and instant threat to the financial system.
What’s inflicting the drop at present? Tariff threats primarily, at the very least that’s what the media is pushing. Now we have identified for a while that this was Trump’s agenda, which begs the query why that is surprising the market a lot since they’re ahead wanting. We noticed the reverse occur when he received the election and the markets pumped, excited by the concept that much less purple tape and beneficial financial insurance policies have been coming.
The fact is there are some basic issues, however the present market motion appears disproportionate to the underlying components, and should not totally mirror the long-term outlook.
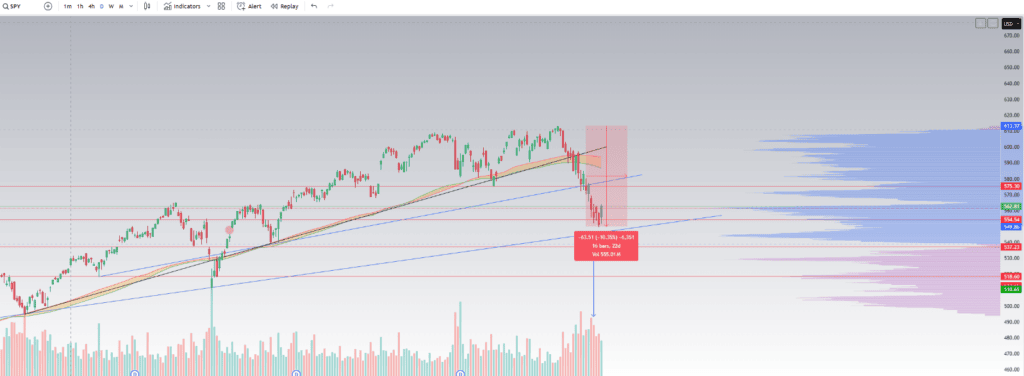
Present drop within the SPYSource: Buying and selling View chart
While a -10% drop doesn’t look like a lot; the outcome may be far more significant to shares inside the S&P 500. Signalling some nice shopping for alternatives on some ”secure” shares.
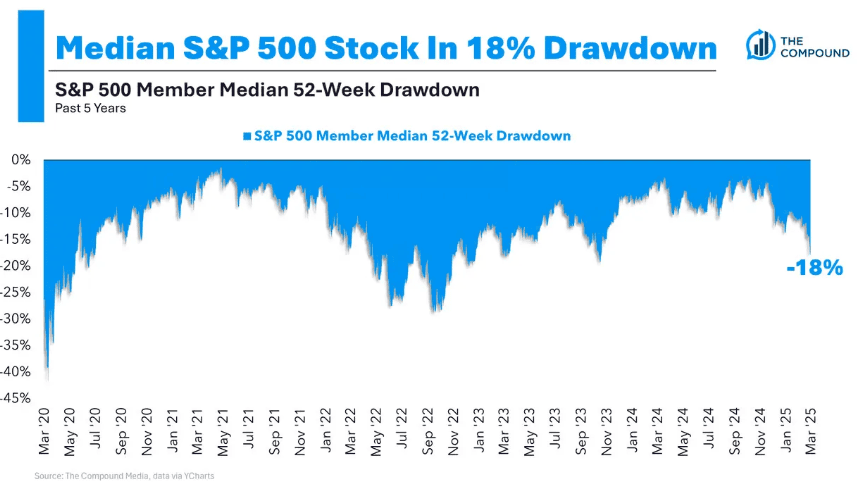
Supply: YCharts
Sentiment
Current information has highlighted some attention-grabbing factors. Within the chart under we will see Michigan College’s change in enterprise situations in a 12 months is now probably the most bearish it’s been in historical past. Let that sink in. The market is extra fearful than Covid, rates of interest and inflation going up. The sentiment at the moment displays a degree of negativity that’s unprecedented in current historical past, even surpassing the challenges seen through the monetary disaster and different main market occasions.
After all, take this with a pinch of salt. A lot of these surveys aren’t my favorite, and I don’t just like the teams or the best way the information is collected, but it surely actually strains up with numerous what we’re seeing and listening to on the market.
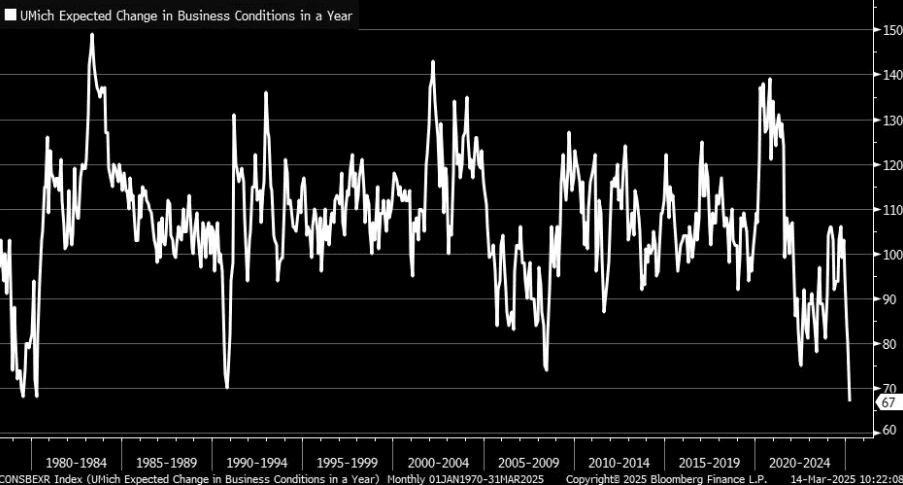
Supply: College of Michigan
That is usually a left leaning base however even the correct facet exhibits a detrimental outlook, simpler to establish once we take a look at their breakdown of client expectations between events within the chart under. Democrats are actually slightly extra… detrimental.
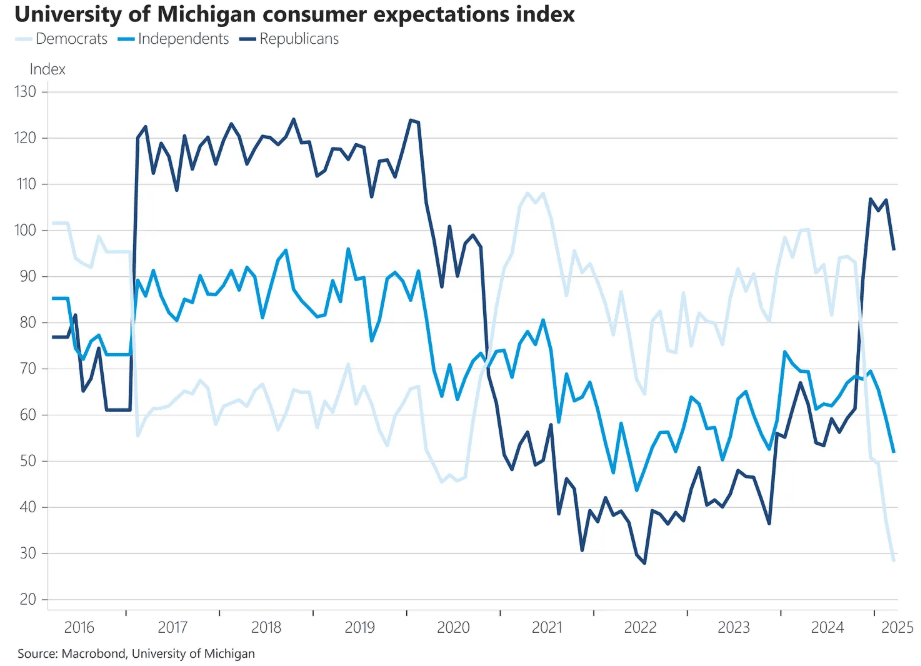
Supply: College of Michigan
One other chart that seems alarming at first look is the Anticipated change in monetary scenario in a 12 months, however paradoxically this degree of worry (Under 100) throughout earlier financial downturns has usually been indicative of the market being near its backside. We are able to overlay that information onto the SPY and discover that in 1979, 1980, 2008, and 2022, the markets have been near peak worry and moved larger quickly after.
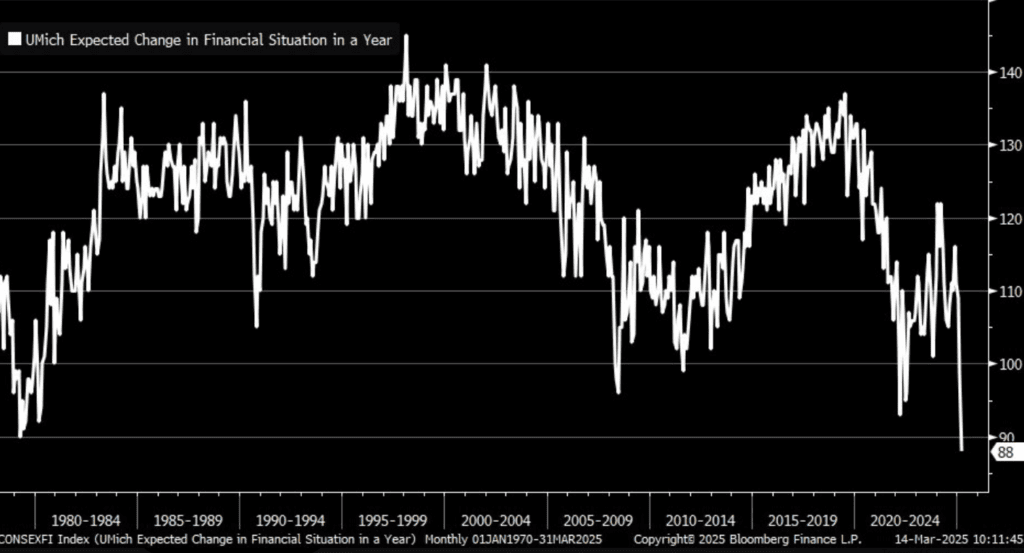
Supply: College of Michigan
Different market sentiment gauges embrace the AAII bull-bear spreads, which has fallen off a cliff. Beforehand when this degree was hit in 2022, the market recovered a number of weeks after. I discover this one probably the most helpful when measuring perceived sentiment. For me, it’s indicator of when is an efficient time to lean into the worry, supplied that the underlying fundamentals are nonetheless on observe after all. Scaling into positions when this metric drops under 20 and scaling out of positions when it’s over 20 is threat administration that is sensible to me.
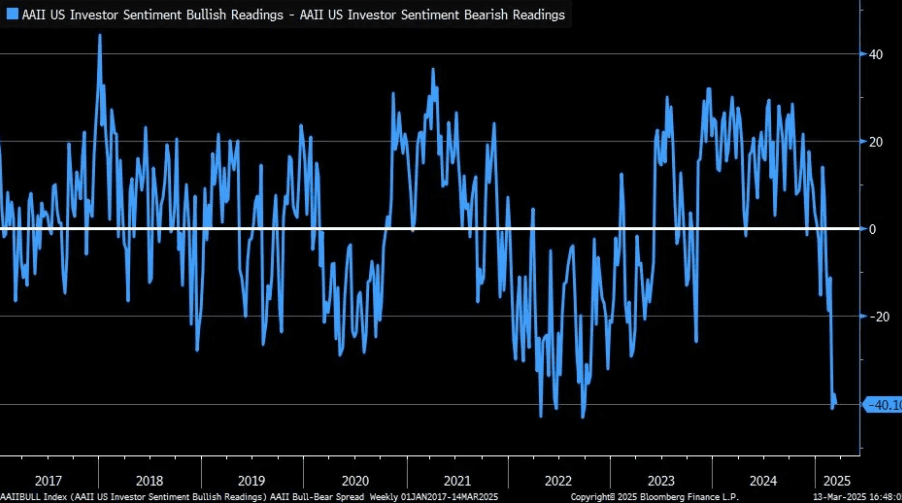
Supply: Bloomberg
When you would like a extra simplistic metric to observe, the worry and greed index provides a much less correct mannequin. Lots of people prefer to quote Buffet ”Be fearful when others are grasping and grasping when others are fearful.” when referring to this one and It’s going to offer you very broad strokes but it surely’s not a nasty place to start out.
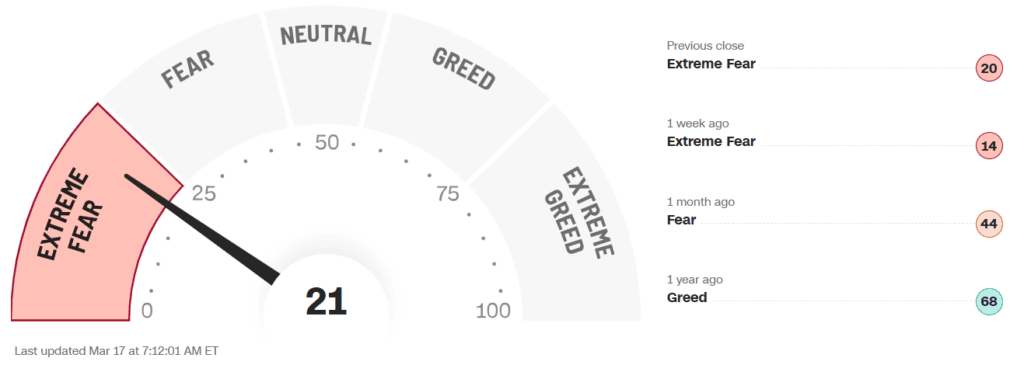
Supply: CNN
We additionally not too long ago bought the New York Fed survey information and you’ll find that by clicking right here. To avoid wasting you from extra charts I’ll stick to providing you with the cliff notes model of the information. The outcomes present a transparent acceleration in perceived threat of upper unemployment throughout most areas and demographics, with contributors additionally extra detrimental about future family funds. Placing ranges for every of those measurements again at late 2022 ranges.
The info offered aligns with established market cycles and provides insights into investor psychology, which generally is a vital affect on market conduct. Sentiment is commonly extra vital than the underlying information and the way buyers understand that information can transfer the market its methods. Headline information creates sharp preliminary reactions, however wise heads take time to kind by the noise to decide. The market generally will catch as much as its mistake in some unspecified time in the future when information is digested and sentiment modifications. This is applicable to the broad market indexes and particular firms.
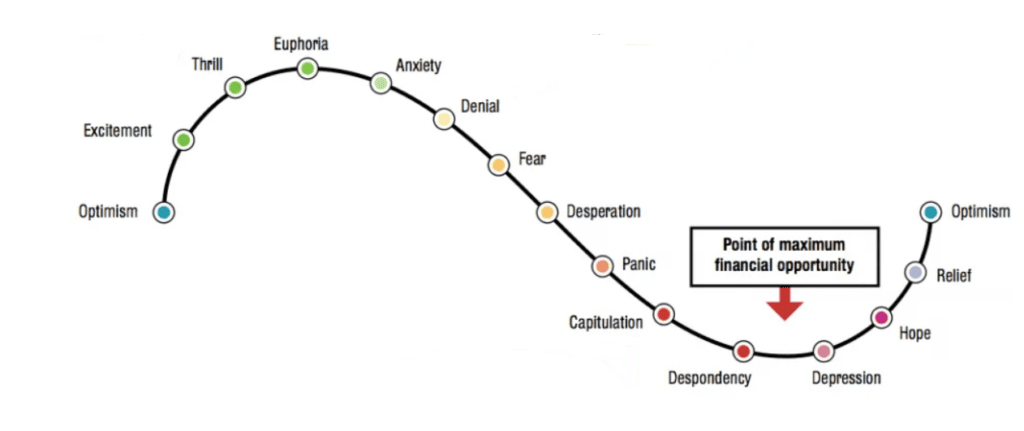
Supply: Understanding financial, market and tremendous cycles | FundCalibre
You will discover charts and information factors like this in all places with little or no effort and the explanation I’m exhibiting you all this information is solely to indicate you that perceived threat is off the charts. Primarily based solely on these charts, one may conclude that there are vital dangers forward. Nevertheless, it’s important to contemplate a wider vary of financial indicators earlier than drawing conclusions.
What triggered the unhealthy sentiment?
The brand new huge unhealthy fear we should cope with is recession. Economists have been yapping about it for an age, and so they couldn’t have been extra improper over the previous few years. Might this be considerably impacted by their reluctance to name the submit Covid financial contraction a recession? Possibly.
Considerations over weak GDP have been partly pushed by the Atlanta Fed’s GDP updates, that are utilized by the Federal Reserve. Whereas this information raises issues, it must be thought-about alongside different financial indicators for a clearer image. It primarily attributes the drop to the commerce steadiness deficit and in the event you dig into the information the imports are skewing these numbers. If we expect for a second why that’s, it doesn’t make a lot sense to base an opinion on that information.
The -2.6% GDP determine raises questions on its accuracy and the components contributing to this drop. Additional evaluation is required to know its implications totally.
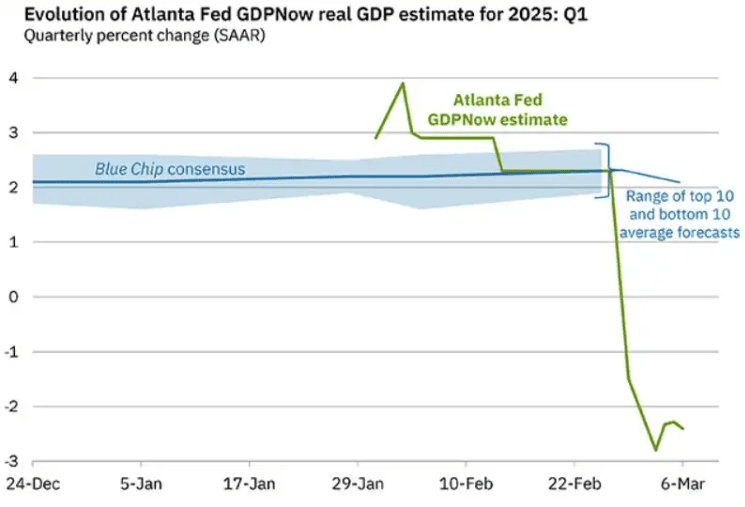
Supply: Atlanta Fed
Considerations over tariffs are affecting firms in sure sectors, prompting them to regulate their methods to keep up margins amid uncertainty. Affected firms ship items in bulk earlier than tariffs are imposed. We noticed this being an enormous problem throughout Covid, exacerbated by delivery constraints. It bought so unhealthy in Covid that stock ranges bought slightly spicy, which induced additional points when demand slowed down. Big shipments of Gold transferring again to the US is a big a part of this too, it’s not simply client items inflicting the numbers to be so off-kilter.
Web exports from the ultimate February print are approach out of character. Displaying enormous imports offsetting exports.
Vital word: There’s clearly a decline in exercise because the finish of February 2025, particularly referring to the buyer, however not as alarming because the preliminary chart signifies and bettering after a drop.
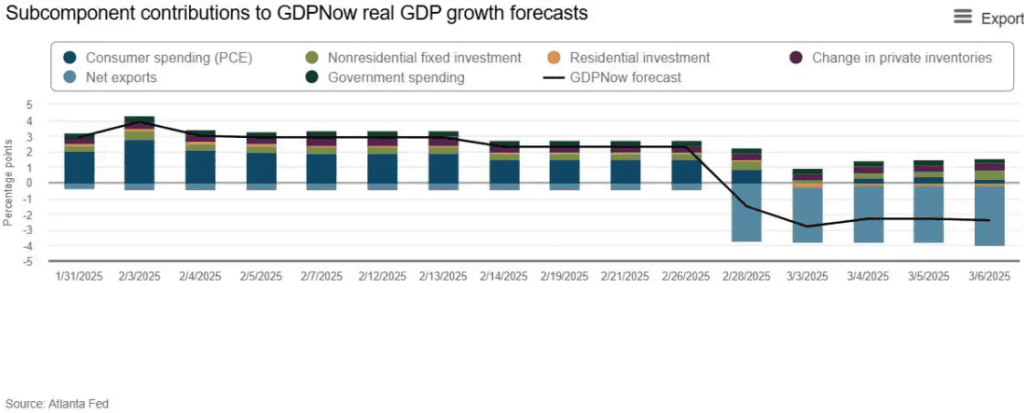
Supply: Atlanta Fed
Why is the underside shut, or at the very least a bounce?
The Fairness Put/Name ratio is again in beneficial steadiness.
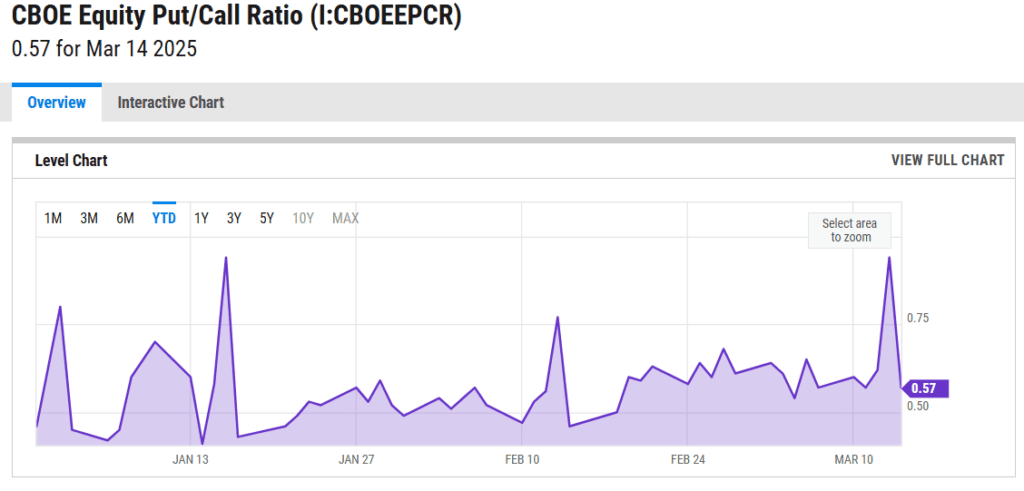
Supply: CBOE Fairness Put/Name Ratio Market Day by day Insights: CBOE Day by day Market Statistics | YCharts
The VIX has cooled off. I’d be happier to see it settle below 20 the decline right here is optimistic to see. If this unhealthy boy begins rising… We’ll be getting extra draw back.
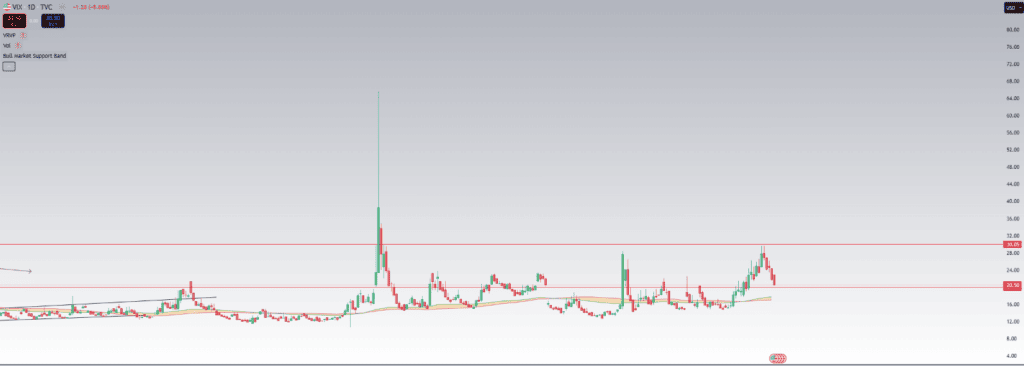
Supply: My TA
Hedge funds have been unwinding positions in single shares on the quickest fee we’ve seen in over 2 years, decreasing their market publicity, however nonetheless sustaining a optimistic outlook. Suggesting they’re simply rolling with the short-term noise, which is pretty normal behaviour for hedge funds. So why am I mentioning this as a optimistic indicator? The excellent news is that they’ll have loads of money to deploy once they sit match. It’s this fashion of threat on investing that drives the V formed recoveries that we frequently see after a correction.
Quantity can also be falling for the SPY, suggesting some vendor exhaustion and the RSI has been at ranges usually solely hit when there’s a powerful bounce or reversal.
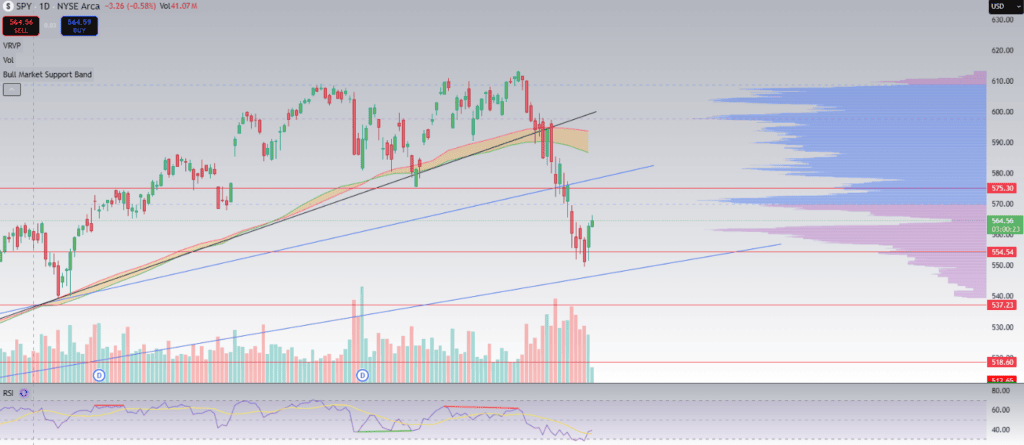
Supply: My TA
I did need to briefly contact on some basic market traits. I’m positive you’ve seen a great deal of charts like this these days, however they stand true. If we take a look at prior quickest 10% drops available in the market, on common 3 months from the drop we’ve a return of 8.2%, 6 months is a 15% return, and one full 12 months is a tidy 19.9% return. This occurs no matter a recession or extra draw back worth motion.
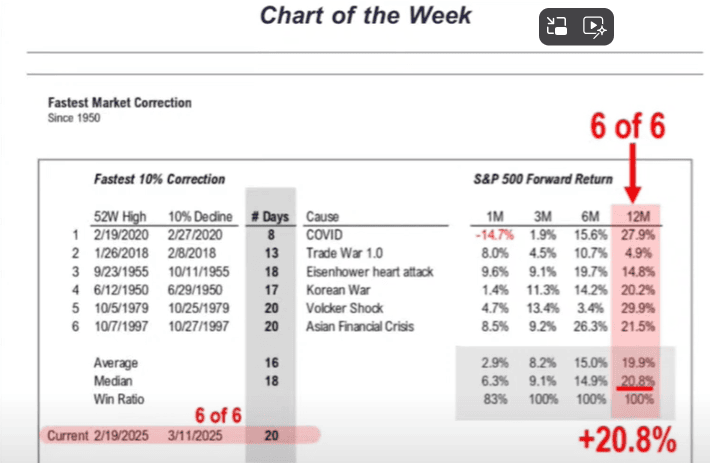
One factor we do know for positive, is these drops present glorious long-term potential for consumers that may deal with the volatility.
Why I’m shopping for the dip
Most individuals are solely taking a look at this drop with a really short-term view. Does that make sense? No. Treasury Secretary Scott Bessent has been very clear on permitting markets to endure some short-term ache for long run acquire. From a Macro perspective, there’s nice advantages in permitting issues to say no over the brief time period and my expectation is that that is being finished for a number of causes. First, to nudge the Fed into chopping extra aggressively and permitting the US debt to be refinanced at decrease charges. Second, Bessent has additionally been very clear on his want to kind out the 10yr and get that fee decrease. A excessive yield places strain on the housing sector, which is a troubled sector proper now. One thing not many individuals point out is that when the yield is low, it may increase inventory costs as a result of the current worth of future earnings is larger. A better yield can result in decrease inventory valuations as the price of capital will increase, making equities much less enticing in comparison with the risk-free return on authorities bonds.
Simply to be clear, I don’t see inflationary dangers to the market. The Fed’s information is considerably lagging (Approx. 45 days behind the Truflation information) so I wouldn’t get hopes up for a right away lower.
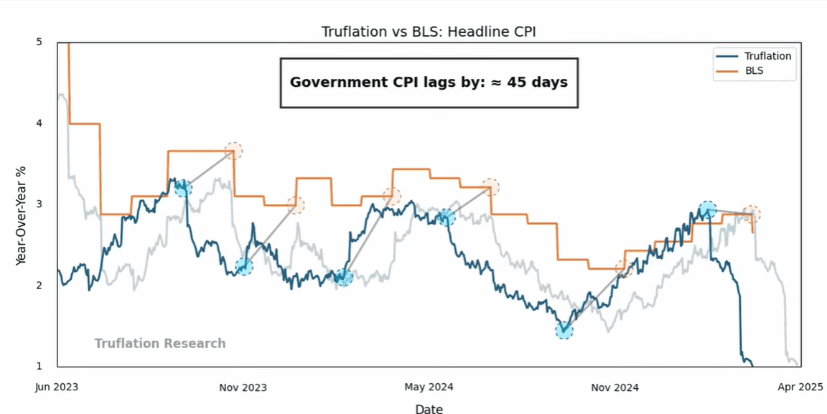
Supply: Truflation US Inflation Index | Truflation
Dangers
Quick time period: A hawkish Fed this week that continues with QT might push us decrease and Trumps tariff replace on April 2nd might stoke up worry.
Long run: The ”mortgage disaster” and locked up actual property sector must be addressed, and US debt must be managed, which is what Bessent is ready on coping with.
Quantitative tightening is seen liquidity depart the system and it’s wanting worrying to me proper now. In all probability the measure I’m most involved with. The M2 measure has bought folks excited however liquidity is extra complicated than that. US cash markets must be sounding some alarm bells to the Fed and it’s actually the guts of the financial system. The SOFR (Repo fee) much less Fed funds unfold has been spiking since July 2024, worth must be secure inside the tram strains as they point out the conventional vary. What does this imply? Basically there received’t be sufficient liquidity to maintain establishments that rely on it, comparable to banks, that are seeing falling reserves. Financial institution reserves peaked at $4.2 trillion however have since misplaced over a trillion {dollars}, falling to $3.25 trillion. It’s advised {that a} drop under $3.2 trillion, which is just $50 billion under present ranges, might set off a black swan occasion.
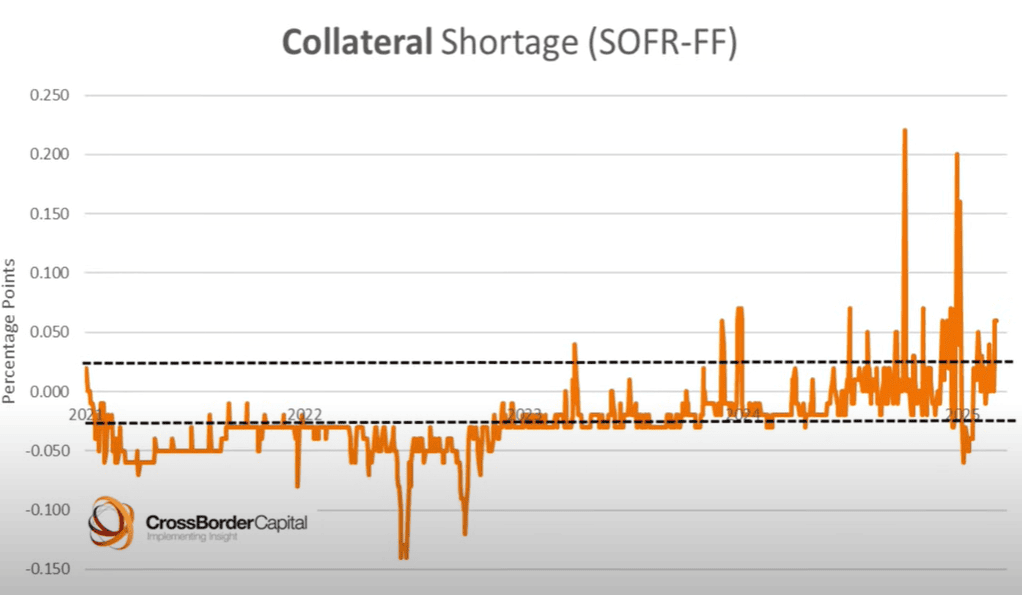
Supply: CrossBorderCapital
There are different components which have exacerbated this although, comparable to reverse repo’s working dry and all these brief time period issuances Janet Yellen left as slightly reward for Bessent falling off too (It’s possible this was an try to spice up Biden’s re-election possibilities), however that’s stepping into complicated territory and a dialogue about hidden QE/QT. Silver lining although, QE beginning ought to alleviate this strain and in the event that they set the steadiness sheet dimension relative to the debt burden as a substitute of sticking to their present shrinking plan, we might have one much less factor to fret about. It’s potential that we might see a restoration quickly. One potential answer to alleviate among the present pressures might be a revaluation of gold, because it hasn’t been adjusted since 1973. This might give the treasury an enormous windfall, assist yields to maneuver decrease so US debt may be refinanced and to allow them to get all the way down to stimulating.
Conclusion
Whereas there should be some draw back dangers, it’s potential that a lot of the market’s current challenges have already been priced in, and my technique doesn’t concentrate on timing the tops or bottoms completely. What I love to do, is catch the meat of a transfer, whether or not it’s particular person shares or indexes. I do know it’s very cliché advising folks to purchase when there’s worry and promote when there’s euphoria, however the actuality is, it’s laborious to not fall into the psychological entice and promote on the lows.
One factor I can say with accuracy is, sentiment strikes the market extra simply and quicker than many actual market contagions, each to the draw back and upside. This does give us numerous volatility, however that may additionally give us numerous alternative and that’s what I see right here. Alternative to purchase extra of my favorite shares with some very beneficiant reductions. Will I’ve the prospect to purchase even cheaper? Possibly, however I don’t need to fear about timing after I’ll do nicely, given sufficient time, shopping for shares I really like over the subsequent 5 years at at present’s costs with a 25% to 50%+ low cost.
This communication is for data and schooling functions solely and shouldn’t be taken as funding recommendation, a private suggestion, or a proposal of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out taking into consideration any explicit recipient’s funding aims or monetary scenario, and has not been ready in accordance with the authorized and regulatory necessities to advertise unbiased analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product aren’t, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.
[ad_2]
Source link


